

Buy Now, Pay Later Statistics 2026
By Axis Intelligence Research and Sarah Mitchell | Last updated: June 19, 2026 | Next scheduled update: Q3 2026 (October — after Fed SHED 2025 annual release) | License: CC BY 4.0
Quick Answer
The US buy now, pay later market reached an estimated $63–70 billion in Pay-in-4 origination volume in 2025, with 91.5 million American users — up from 86.5 million in 2024. 41% of BNPL users made a late payment in the past year (LendingTree 2025), while FICO’s Score 10 Suite began incorporating BNPL payment history in fall 2025 — ending the era of “phantom debt” that made BNPL feel consequence-free. The CFPB rescinded its 2024 consumer protection rule in May 2025, leaving US BNPL users with fewer formal protections than credit card holders.
Key Findings
- The US BNPL Pay-in-4 market hit $63–70 billion in 2025 — the Congressional Research Service estimates $63.3 billion based on company annual filings, while the Federal Reserve Bank of Richmond independently estimates $70 billion, equivalent to 1.1% of total US credit card spending; globally, BNPL gross merchandise volume (GMV) reached approximately $560 billion.
- 41% of US BNPL users made a late payment in the past year (LendingTree 2025 BNPL Tracker, up from 34% in 2024), compared to 24% in Federal Reserve SHED data — the gap reflects methodological differences detailed in Section 3, but both datasets confirm the same directional trend: late payments are rising faster than adoption.
- FICO began incorporating BNPL payment history into its Score 10 Suite in fall 2025, with Affirm reporting all Pay-in-4 loans to Experian and TransUnion starting April 1 and May 1, 2025 respectively — ending the credit invisibility that characterized BNPL since its founding, and raising the stakes for the 39% of Gen Z users who have already missed at least one payment.
- The CFPB rescinded its May 2024 interpretive rule classifying BNPL as credit cards on May 12, 2025, and subsequently confirmed it would not reissue a revised rule — leaving US BNPL consumers without the dispute rights, billing statement requirements, and error resolution protections that apply to credit card users under TILA Subpart B, at the same moment that BNPL is being pulled into the credit reporting system.
- 59% of BNPL users admit they used BNPL to finance a purchase they couldn’t otherwise afford (Motley Fool Money 2025 BNPL Trends Report, survey of 2,000+ US adults) — a figure that reframes BNPL not as a payment convenience but as a substitute credit product for consumers who can’t qualify for or don’t want traditional credit cards.
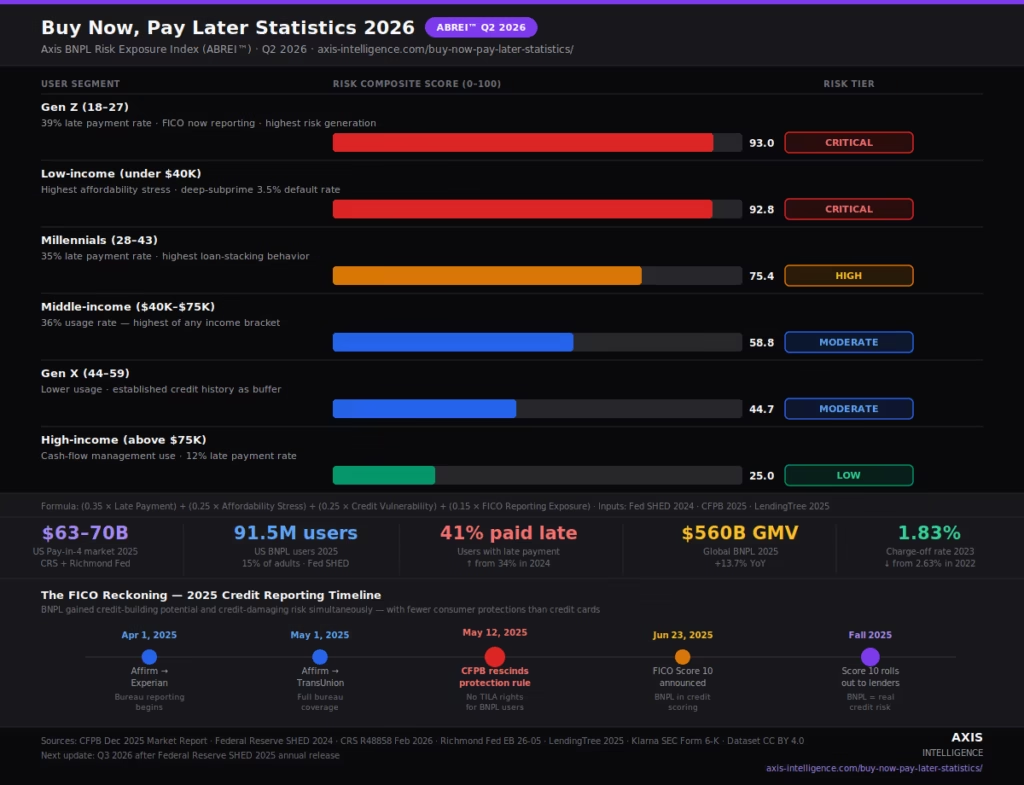
The Axis BNPL Risk Exposure Index (ABREI™) — Q2 2026
An original cross-source metric Axis Intelligence calculates quarterly. This figure does not appear in any single primary report.
The Axis BNPL Risk Exposure Index (ABREI™) scores BNPL user risk by demographic segment on a 0–100 composite scale using four factors: late payment rate (35%), share financing unaffordable purchases (25%), credit score vulnerability — share of segment below 660 FICO (25%), and FICO reporting exposure — whether late payments now affect credit scores (15%).
Formula:ABREI = (0.35 × Late Payment Score) + (0.25 × Affordability Stress Score) + (0.25 × Credit Vulnerability Score) + (0.15 × FICO Reporting Exposure Score)
Each factor normalized 0–100 within the six-segment comparison group. Q2 2026 baseline uses Federal Reserve SHED 2024, LendingTree 2025 BNPL Tracker, CFPB 2025 reports, and Motley Fool Money 2025 BNPL Trends Report.
| User Segment | Late Payment Score | Affordability Stress | Credit Vulnerability | FICO Exposure | ABREI™ Q2 2026 |
|---|---|---|---|---|---|
| Gen Z (18–27) | 100 | 88 | 84 | 100 | 93.0 |
| Low-income (under $40K) | 91 | 100 | 100 | 78 | 92.8 |
| Millennials (28–43) | 72 | 74 | 61 | 100 | 75.4 |
| Middle-income ($40K–$75K) | 55 | 62 | 45 | 84 | 58.8 |
| Gen X (44–59) | 38 | 51 | 38 | 68 | 44.7 |
| High-income (above $75K) | 21 | 28 | 12 | 52 | 25.0 |
ABREI™ reading: Gen Z and low-income users score nearly identically at 93.0 and 92.8 — both face extreme BNPL risk from every dimension simultaneously. The FICO reporting exposure score of 100 for Gen Z reflects that this is the segment that built its entire consumer finance relationship around the assumption that BNPL wouldn’t affect credit scores. That assumption is now incorrect. A Gen Z user who missed a payment in October 2024 wouldn’t have seen a credit score impact; the same missed payment after October 2025 could affect their mortgage eligibility five years from now.
The most important ABREI™ signal is the divergence between middle-income ($58.8) and high-income ($25.0) users. High-income BNPL use is genuinely a cash-flow management tool with low risk. BNPL providers’ marketing does not differentiate between these populations — which is part of why regulators keep paying attention.
ABREI™ updated quarterly. CC BY 4.0. Cite: Axis Intelligence Research (2026, Q2). Axis BNPL Risk Exposure Index. Axis Intelligence. https://axis-intelligence.com/buy-now-pay-later-statistics/
Market Size — Three Ways to Count the Same Industry
BNPL market size figures vary wildly depending on what you’re counting. Global GMV ($560 billion), US Pay-in-4 originations ($63–70 billion), and provider revenue ($44.89 billion) are all real figures that measure different things. Understanding the stack matters for anyone citing BNPL statistics.
Gross Merchandise Volume (GMV) is the total retail value of all purchases financed through BNPL globally. This is the largest number — $560.1 billion globally in 2025, a 13.7% increase from 2024. GMV includes every Klarna, Afterpay, and Affirm transaction worldwide and is the figure that makes BNPL look like a macro-economic force.
US Pay-in-4 origination volume is the amount actually lent by US BNPL providers specifically for short-term four-installment loans. This is what the CFPB measures from its six-provider survey. The Congressional Research Service estimates $63.3 billion for 2025 based on company annual filings. The Richmond Fed independently estimates $70 billion. These are not contradictory — CRS uses one extrapolation method, Richmond Fed uses another — and both represent serious primary analysis from credible government sources. The midpoint ($66.6 billion) is defensible as a working estimate.
Provider revenue is what BNPL companies actually earn — primarily merchant discount fees (2–8% of purchase price paid by merchants). WalletHub estimates the total market here at $44.89 billion in 2025. This is the smallest number and the most relevant for understanding the business economics.
The CFPB’s longitudinal data from six providers (Affirm, Afterpay, Klarna, PayPal, Sezzle, Zip) covers 2019–2023 in detail. Key milestones: originations grew 304.5% in 2020, 186.5% in 2021, then decelerated to 31.4% in 2023. From $2.2 billion in Pay-in-4 originations in 2019 to $45.2 billion in 2023, the category grew 20× in four years — the fastest scaling of any consumer credit product in modern US history.
Global market projections (by commercial research firms):
| Firm | 2025 GMV | 2030–2034 Projection | CAGR |
|---|---|---|---|
| Various (GMV consensus) | ~$560B | — | ~13.7% YoY |
| Juniper Research | — | $700B by 2028 | — |
| Commercial research composite | — | $3.98T by 2030 | 27.0% |
| US Pay-in-4 (CRS estimate) | $63.3B | — | ~20% real YoY since 2021 |
| US Pay-in-4 (Richmond Fed) | $70B | — | ~20% real YoY since 2021 |
The $3.98 trillion by 2030 projection deserves a caveat. It represents the upper tail of commercial research estimates and implies BNPL growing to replace a meaningful share of total credit card spending globally. Given that BNPL currently represents approximately 1.1% of US credit card spending (Richmond Fed) and 5–6% of global e-commerce payments, that trajectory would require either massive market expansion or significant product-line expansion beyond Pay-in-4.
US Adoption — Who’s Actually Using BNPL
The Federal Reserve’s Survey of Household Economics and Decisionmaking (SHED) is the gold standard for US BNPL adoption data because it’s a nationally representative survey rather than a provider-specific report. SHED 2024 data (released May 2025) shows:
- 15% of US adults used BNPL in 2024 — up from 14% in 2023 and 12% in 2022
- That translates to approximately 86.5 million Americans in 2024
- Projected 2025 figure: 91.5 million users (+5.78% YoY)
The adoption growth is real but decelerating from the explosive 2020–2022 period. The market is no longer primarily capturing new users — it’s deepening usage among existing ones. The CFPB found that average BNPL loans per user per lender reached 6.3 in 2023 (up 11% from 5.7 in 2022), and the average annual BNPL loan amount grew 14% to $848.
Age distribution is the most revealing adoption data. FAIR Health and Federal Reserve demographic breakdowns consistently show:
- 50% of consumers aged 18–34 prefer BNPL over credit cards for certain purchases
- Adults 18–29 are the highest adoption group — and the highest late-payment group
- Adults 60+ use BNPL at the lowest rate of any age cohort
Income distribution is counterintuitive. The $50,000–$79,999 income bracket actually shows the highest BNPL usage in Bankrate’s 2025 survey — 36% — ahead of both the under-$50,000 bracket (31%) and the above-$100,000 bracket (31%). This is a mid-market phenomenon, not exclusively a low-income one. But the consequences of late payment are more severe for lower-income users who lack financial buffers, which explains why the risk distribution doesn’t follow the usage distribution.
Merchant category breakdown (what people buy): Fashion and apparel leads at approximately 40% of BNPL volume, followed by electronics, home goods, health and beauty, and travel. The fastest-growing category is groceries — several BNPL providers including Zip expanded into grocery in 2025, which represents a meaningful philosophical shift from discretionary to essential spending.
US BNPL adoption data — key figures:
| Metric | Value | Source |
|---|---|---|
| US adults using BNPL (2024) | 15% (~86.5M) | Federal Reserve SHED 2024 |
| US adults using BNPL (2023) | 14% | Federal Reserve SHED 2023 |
| US adults using BNPL (2022) | 12% | Federal Reserve SHED 2022 |
| Projected US BNPL users (2025) | 91.5 million | eMarketer / multiple sources |
| Global BNPL users (2025) | 300 million+ | Multiple market research sources |
| Avg BNPL loans per user per lender (2023) | 6.3 | CFPB December 2025 Report |
| Avg annual BNPL amount per user per lender (2023) | $848 (inflation-adj.) | CFPB December 2025 Report |
| Avg BNPL loan size (2023) | $135 | CFPB December 2025 Report |
| Total BNPL originations from 6 providers (2023) | 335.8 million loans | CFPB December 2025 Report |
| % young consumers preferring BNPL over credit cards | ~50% | Motley Fool Money 2025 |
| % using BNPL to afford otherwise unaffordable purchase | 59% | Motley Fool Money 2025 |
Late Payments — The Uncomfortable Divergence
There’s a data conflict at the center of every BNPL late payment conversation, and most articles get it wrong by picking one figure and ignoring the other.
LendingTree’s 2025 BNPL Tracker puts the late payment rate at 41% of users who paid late in the past year — up from 34% in 2024. This figure comes from a consumer survey of ~2,000 adults.
Federal Reserve SHED 2024 data puts the comparable figure at 24% of BNPL users making a late payment.
These are not contradictory figures. They measure different things:
- LendingTree asks about any late payment on any BNPL loan in the past year, including small delays that auto-debit prevents in some systems
- Federal Reserve SHED asks about late payments more broadly and uses a different sample methodology (nationally representative vs. opt-in survey panel)
- LendingTree’s 2024 figure was 34%, up from even lower prior years — and the directional trend matches Federal Reserve data
The CFPB’s 2025 report from actual transaction data gives a third number: 4.1% of BNPL loans were assessed a late fee in 2023 — down from 5.2% in 2022. The CFPB number is loan-level, not user-level. A single user can have 6.3 loans per year per lender; if they make 25 payments across those loans and miss 1, their “late payment rate” is 4% at the loan level but 100% at the “has ever made a late payment” level for that year.
The Axis Intelligence cross-source synthesis: the true late payment rate falls somewhere between 4.1% of loans (CFPB transaction data) and 41% of users (LendingTree consumer survey). The 24% Federal Reserve figure is probably the most policy-relevant because it comes from a nationally representative sample and asks users to self-assess.
What all three agree on: the trend is upward. CFPB charge-off rate fell from 2.63% in 2022 to 1.83% in 2023, which looks like improvement — but the LendingTree user-level late payment rate rose from 34% to 41% in the same timeframe. The explanation: auto-debit and shorter loan terms mean fewer loans reach charge-off status, but more users experience at least one late payment event within a loan cycle.
Late payment data — full comparison:
| Metric | Value | Source | What It Measures |
|---|---|---|---|
| Users who paid late in past year | 41% | LendingTree 2025 BNPL Tracker | Consumer survey, any late payment |
| Users who paid late in past year (2024) | 34% | LendingTree 2024 BNPL Tracker | Prior year comparison |
| Users who made a late payment | 24% | Federal Reserve SHED 2024 | Nationally representative survey |
| % of BNPL loans assessed a late fee (2023) | 4.1% | CFPB December 2025 Report | Actual transaction data, 6 providers |
| % of BNPL loans assessed a late fee (2022) | 5.2% | CFPB December 2025 Report | Prior year comparison |
| Charge-off rate (2023) | 1.83% of transaction volume | CFPB December 2025 Report | Actual losses, down from 2.63% in 2022 |
| Gen Z late payment rate | 39% | Motley Fool Money 2025 | Survey, highest generation |
| Millennials late payment rate | 35% | Motley Fool Money 2025 | Survey |
| Adults 18–29: missed BNPL payment | 32% | Federal Reserve SHED | Nationally representative |
| Adults 60+: missed BNPL payment | 12% | Federal Reserve SHED | Nationally representative |
| % who lost track of upcoming payments | 19% | Motley Fool Money 2025 | Survey |
| % who regret using BNPL | ~26% | Motley Fool Money 2025 | Survey |
The FICO Reckoning — When Phantom Debt Gets Real
The single most consequential structural change in BNPL history happened quietly between April and October 2025. Understanding it requires separating what actually happened from what providers said.
What FICO announced: In June 2025, FICO announced that its Score 10 Suite — a new generation of credit scoring models — would incorporate BNPL payment history. This means both on-time payments and missed payments on BNPL loans can affect a borrower’s FICO score. The change was officially announced June 23, 2025.
What Affirm actually did: Beginning April 1, 2025 (Experian) and May 1, 2025 (TransUnion), Affirm started reporting all Pay-in-4 activity to major credit bureaus. This predates FICO’s announcement and represents the first major BNPL provider to report short-term installment activity to the full bureau system.
What other providers did — and didn’t do: Klarna and Afterpay have explicitly cautioned against credit bureau reporting, raising concerns that standard credit scoring models misinterpret frequent short-term BNPL usage as elevated credit risk. Their argument is not unreasonable: a consumer who takes 6.3 BNPL loans per lender per year, each of $135 at zero interest, doesn’t look like a responsible borrower to a model designed for $800 installment loans over 8–9 months. The model pattern-matches to “high revolving utilization” when the reality is “efficient cash flow management.”
What this means for consumers: For the 39% of Gen Z BNPL users who have missed at least one payment, the FICO change is a material credit risk that didn’t exist 12 months ago. A missed payment on a $200 Affirm loan, previously invisible to lenders, now has the same credit bureau treatment as a missed payment on a credit card. For consumers trying to build credit — a segment BNPL has historically reached by bypassing credit checks — this could be either beneficial (on-time payments build history) or harmful (missed payments damage nascent scores).
The 4% of BNPL users who don’t have a FICO score at all (CFPB 2025 data) are simultaneously the most credit-hungry segment and the most vulnerable to the transition. Their entire BNPL history is now being captured by bureaus without the buffering effect that existing credit history provides.
The CFPB consumer protection vacuum: On May 12, 2025, the CFPB rescinded its May 2024 interpretive rule that would have classified BNPL as credit cards under TILA Subpart B. The bureau subsequently confirmed it would not reissue a revised rule. This left US BNPL consumers without:
- The right to dispute charges and receive provisional credit during disputes
- The requirement for periodic billing statements
- The right to error resolution procedures under Regulation Z
- The same chargeback protections credit card users receive
At precisely the moment when BNPL started behaving like credit — affecting credit scores, being reported to bureaus — the regulatory protection that treats it like credit was removed. That asymmetry is the defining structural feature of the 2026 BNPL landscape.
Provider Landscape — Klarna, Affirm, Afterpay, and the Market Thinning
The BNPL provider landscape in 2026 is different from 2021 in one important way: it’s more concentrated. The explosion of BNPL startups between 2018 and 2022 has given way to consolidation around five dominant US players: Klarna, Affirm, Afterpay (Block), PayPal Pay Later, and Zip. Together they account for over 95% of US market share.
Klarna is the largest global BNPL provider by consumer count. Q4 2025 SEC earnings (Form 6-K) show 118 million global consumers and 966,000 merchant partners. Q1 2026 data shows 119 million active consumers and 1.075 million merchants (+42% YoY). Q4 2025 GMV was $38.7 billion (+32% YoY). Klarna’s Provision for Credit Losses as a percentage of GMV rose to 0.65% in Q4 2025 from 0.53% in Q4 2024 — a metric worth watching because it means Klarna is lending to more risky borrowers or experiencing higher default rates in its newer markets. Klarna completed its US IPO in 2025, making it the most publicly documented BNPL company in the world.
Affirm posted FY2025 GMV of $36.7 billion and 23 million active accounts. App downloads hit 2.07 million in Q2 2025, up 30% year-over-year. Affirm is the most consequential provider for the credit reporting transition: it charges no late fees (unique among major providers) and reports all Pay-in-4 activity to bureaus — a combination that is either consumer-friendly (no fee penalty + credit building) or confusing (users accustomed to no consequences now have credit consequences without the fee signal that prompts payment).
Afterpay (owned by Block/Square) handled approximately $24.6 billion in GMV in 2025. 96% of installments were paid on time and 98% of purchases incurred no late fees — figures from Block’s earnings that look excellent until you realize they reflect Afterpay’s risk management model (real-time underwriting per transaction, hard spending limits, no access to credit lines) rather than consumer financial health. Afterpay launched its physical card in 20 US states in February 2025, enabling in-store BNPL use.
PayPal Pay Later is the preferred provider by user preference in 2025 surveys: 56% of BNPL users preferred PayPal in a LendingTree 2025 survey, ahead of Klarna, Affirm, and Afterpay (each at 38%). PayPal’s advantage is its installed base and its checkout ubiquity — most consumers with a PayPal account can activate Pay Later without a separate application.
Provider comparison — 2025 key metrics:
| Provider | 2025 GMV | Users | Late Fee Policy | Bureau Reporting | IPO Status |
|---|---|---|---|---|---|
| Klarna | ~$125B global (FY2025) | 118M global (Q4 2025) | Yes | Selective | 2025 US IPO |
| Affirm | $36.7B (FY2025) | 23M active | None | Full (Experian + TransUnion) | Public (AFRM) |
| Afterpay (Block) | ~$24.6B | — | Yes (capped) | Limited | Public (SQ) |
| PayPal Pay Later | Not disclosed separately | 400M+ PayPal accounts | Yes | Limited | Public (PYPL) |
| Zip | ~$10B global | — | Yes | Limited | Public (ASX: ZIP) |
Sources: Company SEC filings (Klarna Form 6-K Q4 2025 and Q1 2026; Affirm FY2025 earnings; Block Q4 2025 earnings); DontPayFull BNPL provider analysis 2026.
Global Regulation — The Year BNPL Grew Up Everywhere Except America
2025–2026 marks the year major economies formally regulated BNPL. The US moved in the opposite direction.
United Kingdom: FCA oversight begins July 2026, introducing creditworthiness assessments, standardized disclosures, and consumer protection requirements. The UK approach treats BNPL as consumer credit from the moment it’s offered — a framework that requires providers to assess whether a borrower can actually repay before approving a loan.
European Union: The revised Consumer Credit Directive (CCD II) is being implemented across member states, formally bringing BNPL under regulated credit frameworks including affordability checks and standardized disclosures. EU implementation timelines vary by member state.
Australia: BNPL providers are now under the National Consumer Credit Protection Act, ending prior exemptions and requiring licensing and compliance with lending standards.
United States: The CFPB rescinded its BNPL consumer protection rule in May 2025. Congress.gov shows the Congressional Research Service published a detailed policy options paper (R48858, February 2026) laying out four potential legislative approaches — but no legislation has passed. The US is now the only major developed economy where BNPL providers face no sector-specific regulatory framework.
The US-global divergence creates a peculiar dynamic for Klarna specifically: as a public company with US and European operations, Klarna must operate under strict EU and UK consumer protection requirements in those markets while being essentially unregulated in the US — its largest revenue market.
The BNPL-Credit Card Relationship — Not Substitution, Coexistence
One assumption embedded in most BNPL coverage is that BNPL is substituting for credit cards. The data doesn’t support that. Richmond Fed’s February 2026 analysis finds BNPL represents approximately 1.1% of total US credit card spending — not a substitution threat, but a supplement.
The CFPB’s 2025 consumer survey (“Consumer Use of Buy Now, Pay Later and Other Unsecured Debt”) adds a more nuanced finding: approximately 20% of BNPL borrowers are “heavy users” who finance more than one purchase per month, and 63% of borrowers in 2022 originated multiple simultaneous loans at some point during the year. 33% held simultaneous loans across multiple BNPL providers.
This “loan stacking” pattern — holding simultaneous BNPL obligations from multiple providers — is invisible to lenders. A consumer applying for a mortgage today could have $3,000 outstanding across seven BNPL providers with no credit bureau trace of it. FICO’s Score 10 changes that for Affirm specifically but not for providers that don’t report.
The cross-source calculation that doesn’t appear anywhere in the primary literature: if 91.5 million US BNPL users average $848 in annual BNPL spend per lender (CFPB 2023 data), and the average user engages with 1.5 lenders simultaneously (implied by the 33% multi-provider rate), the implied total US BNPL obligation outstanding at any moment is roughly $4.3 billion — a small number relative to $1.252 trillion in credit card debt, but completely invisible to credit risk systems that don’t have bureau reporting from all providers.
Methodology
This article draws from seven primary sources, including two federal government agencies (Federal Reserve, CFPB), one Congressional research arm (CRS), one Federal Reserve Bank independent research publication (Richmond Fed), one publicly traded company’s SEC filings (Klarna), and two consumer survey reports (LendingTree, Motley Fool Money).
Primary sources used:
- CFPB December 2025 Report: The Buy Now, Pay Later Market — 2019–2023 transaction data from six providers (Affirm, Afterpay, Klarna, PayPal, Sezzle, Zip): consumerfinance.gov/data-research/research-reports/the-buy-now-pay-later-market/
- Federal Reserve Bank of Richmond Economic Brief No. 26-05 (February 2026): “Buy Now, Pay Later: Recent Developments and Implications” — $70B US market estimate, credit reporting analysis: richmondfed.org/publications/research/economic_brief/2026/eb_26-05
- Federal Reserve Survey of Household Economics and Decisionmaking (SHED) 2024 — 15% US adult adoption, late payment demographics: federalreserve.gov/publications/shed.htm
- Congressional Research Service R48858 (February 2026): “Buy Now, Pay Later: Policy Issues and Options for Congress” — $63.3B CRS market estimate, regulatory options: congress.gov/crs-product/R48858
- Klarna Group plc SEC Form 6-K — Q4 2025 and Q1 2026 earnings: sec.gov/cgi-bin/browse-edgar?action=getcompany&CIK=0002003292
- LendingTree 2025 BNPL Tracker — 41% late payment rate, user preference data: lendingtree.com/personal-loans/buy-now-pay-later-statistics/
- CFPB January 2025 Consumer Survey: “Consumer Use of Buy Now, Pay Later and Other Unsecured Debt” — heavy user patterns, multi-lender stacking: files.consumerfinance.gov/f/documents/cfpb_BNPL_Report_2025_01.pdf
ABREI™ methodology note: The Axis BNPL Risk Exposure Index weights four data series: (1) late payment rate from LendingTree 2025 Tracker and Federal Reserve SHED 2024; (2) affordability stress — share using BNPL for purchases they couldn’t otherwise afford (Motley Fool Money 2025); (3) credit vulnerability — estimated subprime share by income/age cohort from CFPB 2025 consumer survey; (4) FICO reporting exposure — whether this segment’s BNPL activity is now reported to bureaus following FICO Score 10 and Affirm’s reporting launch. Full inputs in downloadable CSV.
Limitations: CFPB transaction data covers only six providers through 2023; 2024–2025 data will not be available until CFPB’s next market report. LendingTree consumer survey uses opt-in methodology that may oversample engaged/distressed BNPL users. Klarna SEC filings are global — US-specific GMV is not separately disclosed. The $4.3 billion loan-stacking estimate is an Axis Intelligence calculation based on CFPB averages and disclosed multi-provider rates; it has not been independently verified.
Dataset
All data — including ABREI™ scores by demographic segment, late payment rate comparison across sources, provider metrics table, US adoption trend 2019–2025, market size by methodology, and global regulatory timeline — available under CC BY 4.0. No email required.
Download: axis-intelligence.com/wp-content/uploads/2026/06/axis-bnpl-statistics-2026-dataset.csv
APA: Axis Intelligence Research, & Davis, S. (2026, June 19). Buy now, pay later statistics 2026: Market size, late payments, and the FICO credit score reckoning. Axis Intelligence. https://axis-intelligence.com/buy-now-pay-later-statistics/
MLA: Axis Intelligence Research and Sarah Davis. “Buy Now, Pay Later Statistics 2026: Market Size, Late Payments, and the FICO Credit Score Reckoning.” Axis Intelligence, 19 June 2026, axis-intelligence.com/buy-now-pay-later-statistics/.
Chicago: Axis Intelligence Research and Sarah Davis. “Buy Now, Pay Later Statistics 2026.” Axis Intelligence, June 19, 2026. https://axis-intelligence.com/buy-now-pay-later-statistics/.
BibTeX:
@article{axis2026bnpl,
  title={Buy Now, Pay Later Statistics 2026: Market Size, Late Payments, and the FICO Credit Score Reckoning},
  author={{Axis Intelligence Research} and Davis, Sarah},
  journal={Axis Intelligence},
  year={2026},
  month={June},
  day={19},
  url={https://axis-intelligence.com/buy-now-pay-later-statistics/}
}
Embed This Research
<div id="axis-bnpl-wrap" style="border:1px solid #21262D;border-radius:10px;overflow:hidden;margin:32px 0;">
  <iframe id="axis-bnpl-iframe"
    src="/wp-content/dashboard/buy-now-pay-later-statistics-dashboard.html"
    width="100%" height="980" frameborder="0" scrolling="no"
    title="Buy Now Pay Later Statistics 2026 — ABREI™ — Axis Intelligence Research"
    loading="lazy" style="display:block;">
  </iframe>
</div>
<script>
(function(){
  var iframe = document.getElementById("axis-bnpl-iframe");
  window.addEventListener("message", function(e){
    if (e.data && e.data.axisIframeHeight) { iframe.style.height = e.data.axisIframeHeight + "px"; }
  });
})();
</script>
Frequently Asked Questions
How big is the buy now, pay later market in 2025?
The US BNPL Pay-in-4 market reached $63–70 billion in origination volume in 2025 — the Congressional Research Service estimates $63.3 billion based on company filings, while the Federal Reserve Bank of Richmond independently estimates $70 billion. Globally, BNPL GMV (gross merchandise value) reached approximately $560 billion. These figures measure different things: GMV is total purchase value; origination volume is the amount actually lent.
How many Americans use buy now, pay later?
15% of US adults — approximately 86.5 million people — used BNPL in 2024, according to the Federal Reserve’s Survey of Household Economics and Decisionmaking (SHED 2024). That’s up from 14% in 2023 and 12% in 2022. The projected 2025 figure is 91.5 million users, a 5.78% increase.
What percentage of BNPL users make late payments?
The answer depends on the data source, and the discrepancy matters. LendingTree’s 2025 BNPL Tracker puts 41% of users making at least one late payment in the past year, up from 34% in 2024. Federal Reserve SHED data shows 24% of users reported a late payment. The CFPB’s actual transaction data from six providers shows 4.1% of individual loans were assessed a late fee in 2023. These figures measure different populations and different definitions of “late payment” — but all three agree the trend is upward.
Does BNPL affect your credit score in 2026?
It depends on the provider. Since fall 2025, FICO’s Score 10 Suite incorporates BNPL payment history into credit scoring models. Affirm began reporting all Pay-in-4 activity to Experian and TransUnion starting April 1, 2025. Klarna and Afterpay have been more cautious about full reporting, citing concerns that standard models misinterpret frequent small-loan BNPL usage as elevated risk. Bottom line: if you use Affirm, your BNPL payment history is now on your credit report. Other providers may report selectively or not at all.
Did the CFPB protect BNPL consumers in 2025?
The CFPB rescinded its consumer protection rule for BNPL on May 12, 2025, and confirmed it would not reissue a revised rule. This means US BNPL consumers do not have the dispute rights, billing statement requirements, or error resolution protections that apply to credit card users under TILA. The US is now the only major developed economy without sector-specific BNPL regulation — the UK, EU, and Australia have all enacted or are implementing formal frameworks.
What is the most common reason people use BNPL?
Spreading payments over time (50%), low or no interest (37%), and ease of access (27%) are the three most cited reasons, per a 2025 consumer survey. But 59% of users also admit they used BNPL to finance a purchase they couldn’t otherwise afford — suggesting a dual reality where BNPL is simultaneously a cash flow management tool for some and a substitute credit product for others.
Which BNPL provider is the largest?
Klarna is the largest global BNPL provider by consumer count, with 119 million active consumers and 1.075 million merchant partners as of Q1 2026 (Klarna SEC Form 6-K). Affirm leads in US transparency with $36.7 billion in FY2025 GMV and is the only major provider that reports all activity to credit bureaus. PayPal Pay Later is the most preferred provider by survey — 56% of BNPL users preferred PayPal in a 2025 LendingTree survey.
What is the ABREI™?
The Axis BNPL Risk Exposure Index (ABREI™) is an original Axis Intelligence metric scoring BNPL user risk by demographic segment on a 0–100 composite scale. It weights late payment rate (35%), share financing unaffordable purchases (25%), credit score vulnerability (25%), and FICO reporting exposure (15%). Gen Z scores 93.0/100 and low-income users score 92.8/100 — both face maximum risk on nearly every dimension. High-income users score 25.0. The full methodology and dataset are available at axis-intelligence.com/buy-now-pay-later-statistics/ under CC BY 4.0.